
What it does
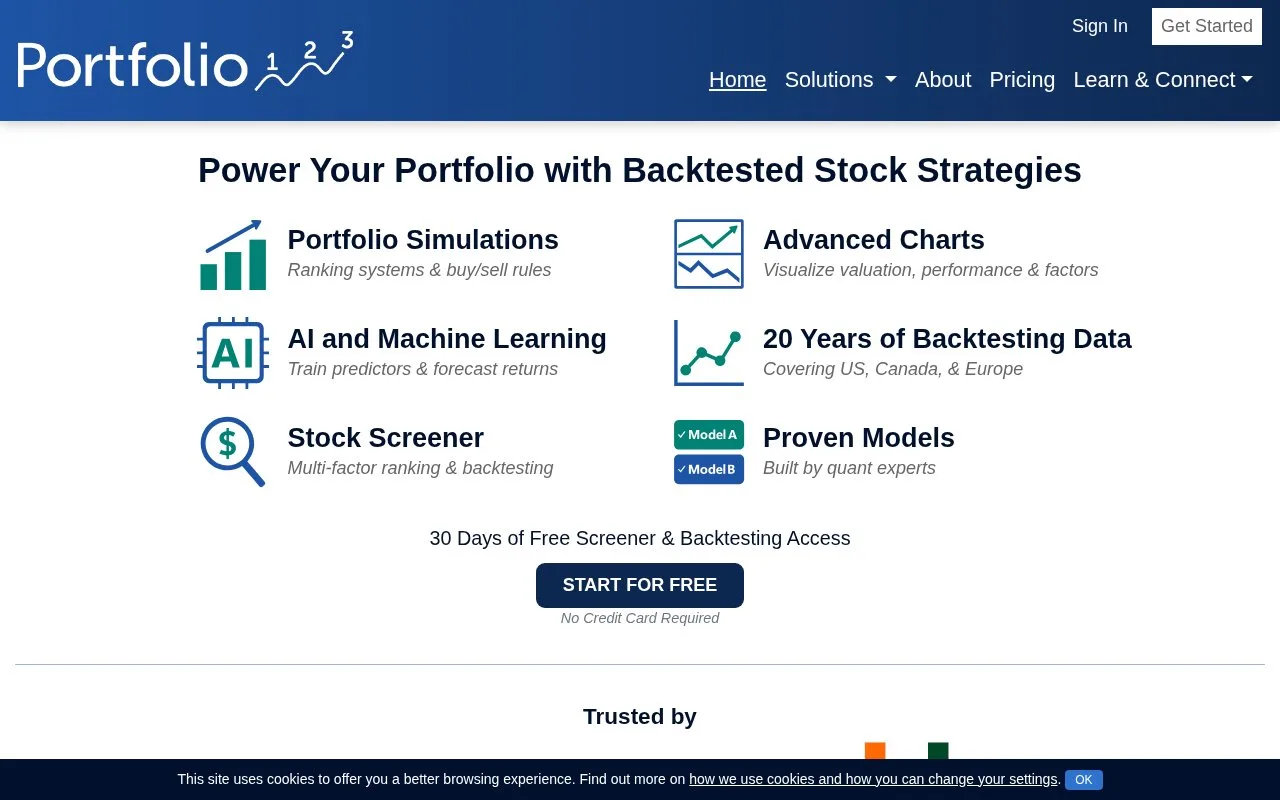
Portfolio123 combines stock screening, factor rankings and rules-based portfolio research in a browser. Investors can build formulas, compare historical strategies and study financial data across US, Canadian and European markets. Portfolio rules control how a ranking becomes a simulated set of holdings.
A ranking system scores the research universe; portfolio rules determine what a simulation buys, holds and sells. Portfolio123 lets you work on both layers. Its formula editor uses a spreadsheet-like approach, with predefined factors and custom calculations, so a research model does not have to begin with Python code.
Choose whether a factor ranks companies across the full universe, within a sector or within an industry. A strategy can then combine a custom universe, buy and sell rules, position sizing and hedging. Commission and slippage assumptions belong in the comparison because apparently similar models can produce different results after trading costs. The historical datasets include point-in-time fundamentals, estimates and corporate actions.
Book of Strategies brings several models together with chosen weights and correlation analysis. That is useful when the question concerns the relationship between strategies rather than the best result from one ranking. Broker-connected management is a separate stage from researching a historical simulation.
The homepage offers a 30-day Screener and Backtest trial without a credit card. Registration is required to build and retain research. Check the current subscription options before committing to a particular data region or research allowance.
Strengths
- Separates factor rankings from portfolio buy, sell and sizing rules
- Supports formula-based research without requiring Python
- Book of Strategies compares weighted combinations and correlations
Best for
- Investors developing rules-based stock screens
- Researchers comparing factor models and portfolio simulations
Sources
- Portfolio123 research scope and 30-day trial (Oct 27, 2026)
- Portfolio123 ranking, screening and simulation controls (Oct 27, 2026)